 WomenBet
The Kelly Criterion
 Available in US
Most bankroll management advice boils down to simple rules: bet 1-3% of your bankroll per wager, keep your unit sizes consistent, don't chase losses. These guidelines work well for recreational bettors. But what if you wanted a mathematically optimal approach—one that maximizes your long-term growth rate while managing risk of ruin? That's where the Kelly Criterion comes in.
Developed by Bell Labs researcher John Kelly in 1956, the Kelly Criterion is a formula that calculates the theoretically optimal percentage of your bankroll to bet based on your edge and the odds offered. It's been adopted by professional gamblers, Wall Street traders, and investment managers as one of the most rigorous approaches to capital allocation when facing uncertain outcomes with positive expected value.
This article explains how the Kelly formula works, when and how to use it for sports betting, and why most practitioners use modified versions rather than the full formula.
The Basic Concept
At its core, the Kelly Criterion answers a fundamental question: if you have an edge, how much should you bet to maximize long-term bankroll growth without risking ruin?
Bet too little, and you're not capitalizing on your advantage—your bankroll grows slower than it could. Bet too much, and a losing streak can devastate you, potentially wiping out your bankroll before the math has time to work in your favor. The Kelly formula finds the sweet spot that maximizes expected geometric growth rate.
The key insight is that optimal betting isn't about maximizing expected value on any single bet—it's about maximizing the compound growth of your bankroll over many bets. This requires balancing aggression (betting more when you have edge) with preservation (not betting so much that losses devastate you).
The Kelly Formula
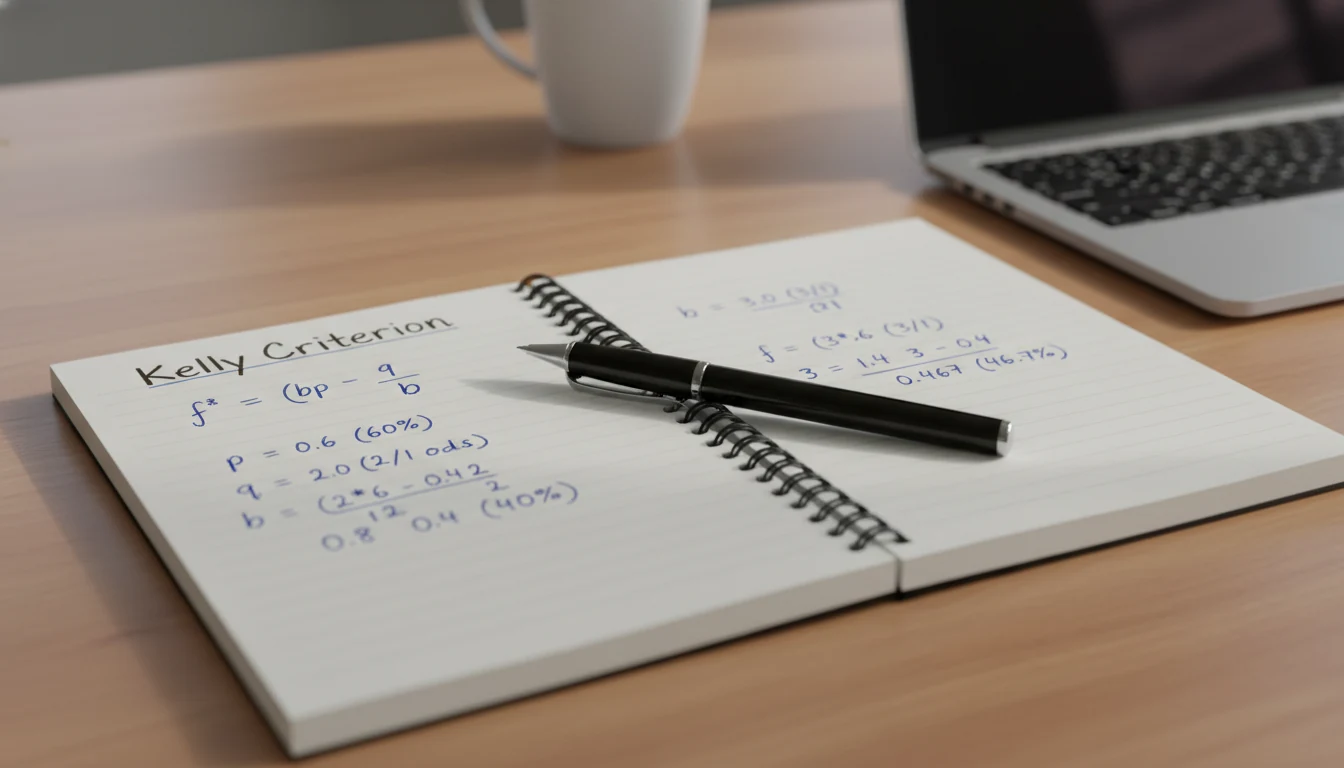
The standard Kelly formula for sports betting is:
f = (bp - q) / b
Where:
f = the fraction of your bankroll to bet
b = the decimal odds minus 1 (or the profit you'd make per dollar wagered)
p = your estimated probability of winning
q = your probability of losing (which equals 1 - p)
Let's work through an example. Suppose you believe a team has a 55% chance of winning, and the sportsbook offers +110 odds (which means you'd profit $1.10 for every $1 wagered, so b = 1.10).
p = 0.55 (your estimated win probability)
q = 0.45 (your estimated loss probability)
b = 1.10 (profit per dollar wagered)
f = (1.10 × 0.55 - 0.45) / 1.10
f = (0.605 - 0.45) / 1.10
f = 0.155 / 1.10
f = 0.141
The Kelly formula suggests betting 14.1% of your bankroll on this wager.
Why Kelly Often Recommends Too Much
That 14.1% recommendation probably seems aggressive—and it is. Full Kelly betting produces optimal long-term growth mathematically, but it also produces stomach-churning volatility along the way.
Consider what happens if you bet 14% of your bankroll per bet and hit a losing streak of five bets in a row. Your bankroll drops to about 47% of where it started. That's not unusual variance; with a 55% win rate, you'll experience five-game losing streaks regularly over a long betting career.
Research shows that a Kelly bettor has roughly a 1-in-3 chance of halving their bankroll before doubling it. While the math eventually works out over infinite bets, most bettors can't stomach—or survive—the intermediate swings.
More importantly, the Kelly formula assumes you know your true edge precisely. In sports betting, you're estimating probabilities based on imperfect information. If you think you have a 55% edge but actually only have 51%, betting full Kelly based on your inflated estimate leads to significant overbetting and potential ruin.
Fractional Kelly: The Practical Solution
Because of these concerns, almost no serious bettor uses full Kelly. Instead, they use "fractional Kelly"—betting some fraction of the Kelly-recommended amount.
Half Kelly (0.5×) cuts the recommended bet size in half. If full Kelly suggests 14%, half Kelly suggests 7%. This dramatically reduces volatility while still capturing most of the growth benefits. Research suggests half Kelly achieves about 75% of full Kelly's long-term growth rate with substantially less variance.
Quarter Kelly (0.25×) is even more conservative. If full Kelly suggests 14%, quarter Kelly suggests 3.5%. This approaches the volatility levels of traditional fixed-percentage betting while still scaling bet size based on perceived edge.
Tenth Kelly (0.1×) is extremely conservative, essentially functioning like cautious flat betting with a mathematical veneer. Some practitioners recommend this for bettors who are uncertain about their edge estimates.
The right fraction depends on your confidence in your probability estimates, your risk tolerance, and your emotional ability to handle variance. Most serious bettors land somewhere between quarter Kelly and half Kelly.
Calculating Your Edge
The Kelly formula is only as good as your probability estimates. Garbage in, garbage out. If you overestimate your edge, you'll overbet and potentially go broke. If you underestimate your edge, you'll underbet and leave growth on the table.
For sports betting, there are two main approaches to estimating probabilities.
Using sharp market odds as a baseline. The sharpest sportsbooks (particularly offshore books with high limits and low margins) offer odds that closely approximate true probabilities. By removing the vig from these lines, you can derive "fair" odds that represent market consensus on probability. If you're getting better odds elsewhere, that difference represents potential edge.
For example, if a sharp book's no-vig line implies a team has a 48% chance to win, but you can bet them at odds implying only 44% probability elsewhere, you might have a 4% edge. This approach requires less personal handicapping skill—you're essentially arbitraging between sharp and soft books.
Building your own probability models. More sophisticated bettors develop their own models that estimate win probabilities based on team statistics, situational factors, and other variables. When your model disagrees with the market, that disagreement represents potential edge.
This approach requires significant expertise and track record validation. You need to demonstrate, over hundreds of bets, that your probability estimates are actually more accurate than the market's before trusting them for Kelly calculations.
A Practical Kelly Example
Let's walk through how a bettor might actually use Kelly in practice.
You've been tracking your WNBA betting for a season and have demonstrated a consistent edge. Your records show that when you estimate a team has a 58% chance to win, they've historically won about 58% of the time over a meaningful sample. You trust your probability estimates.
Today, you assess that the Indiana Fever have a 58% chance to beat the Chicago Sky. The sportsbook offers +105 on Indiana (implying about 48.8% probability by their assessment).
Running the Kelly formula:
p = 0.58
q = 0.42
b = 1.05
f = (1.05 × 0.58 - 0.42) / 1.05 = (0.609 - 0.42) / 1.05 = 0.18
Full Kelly suggests 18% of your bankroll. But you're using quarter Kelly to be conservative:
0.18 × 0.25 = 0.045, or 4.5% of your bankroll.
With a $2,000 bankroll, your bet would be $90.
Notice how this differs from flat percentage betting. If you always bet 2% of your bankroll, you'd bet $40 regardless of edge. Kelly (even fractional Kelly) has you betting more when perceived edge is larger, theoretically maximizing growth.
When Kelly Doesn't Apply
The Kelly Criterion has important limitations that affect its applicability to sports betting.
It assumes you know true probabilities. In reality, you're estimating, and estimation errors compound dangerously. Overconfidence is the most common reason Kelly-based betting fails.
It assumes infinite bankroll divisibility. Kelly might recommend betting 2.37% of your bankroll, but you can't bet $23.70 if the minimum is $25. These rounding effects matter less with larger bankrolls but can significantly impact small ones.
It assumes you can always bet the optimal amount. Sportsbooks limit winners; you may not be able to bet as much as Kelly recommends even if you wanted to.
It optimizes for geometric growth, not utility. Kelly maximizes long-term bankroll growth but doesn't account for your personal risk preferences. If you'd rather grow more slowly with less volatility, Kelly isn't optimizing for what you actually want.
It assumes independent bets. If you're betting multiple correlated events (like three games from the same sport on the same day), the standard Kelly formula doesn't properly account for the correlation between outcomes.
Try out exciting womens soccer lines.
Kelly for Recreational Bettors
Should recreational bettors use the Kelly Criterion? Probably not in its formal mathematical form.
The formula requires accurate probability estimates, and most recreational bettors don't have validated track records demonstrating their estimates are reliable. Using Kelly with unreliable estimates is worse than flat betting—you'll overbet when you're overconfident and potentially blow your bankroll faster than you would with simpler methods.
However, the Kelly concept offers valuable intuition even if you don't use the formula. The idea that bet size should scale with edge—bet more when you have more confidence based on genuine analysis, less when you're less certain—is sound even applied qualitatively rather than mathematically.
A practical approach for recreational bettors: stick to flat percentage betting (1-3% per bet) as your baseline, but allow yourself to bet up to double your standard amount on rare occasions when your analysis is exceptionally strong and supported by evidence. This captures some of the Kelly logic without requiring precise probability estimates.
Kelly Criterion Strategy: Practical Takeaways for Bankroll Management
The Kelly Criterion represents mathematically optimal betting for maximizing long-term bankroll growth. Its formula elegantly balances aggression and preservation, betting more with greater edge while protecting against ruin.
In practice, pure Kelly is too aggressive for most bettors. Fractional Kelly—betting 25-50% of the Kelly-recommended amount—provides most of the growth benefits with manageable volatility. But even fractional Kelly requires trustworthy probability estimates that most recreational bettors haven't developed.
Think of Kelly as an advanced tool for bettors who have demonstrated edge over meaningful sample sizes and want to optimize their capital deployment. If that's you, fractional Kelly can improve on simple flat betting. If you're still developing your handicapping skills, stick to conservative fixed-percentage betting until your track record justifies more sophisticated approaches.
Either way, understanding Kelly teaches a crucial lesson: bet sizing matters as much as bet selection. Finding edge is only half the battle; deploying your capital intelligently determines whether that edge translates to long-term profit.
Avoid bad losing streaks using women bet.
